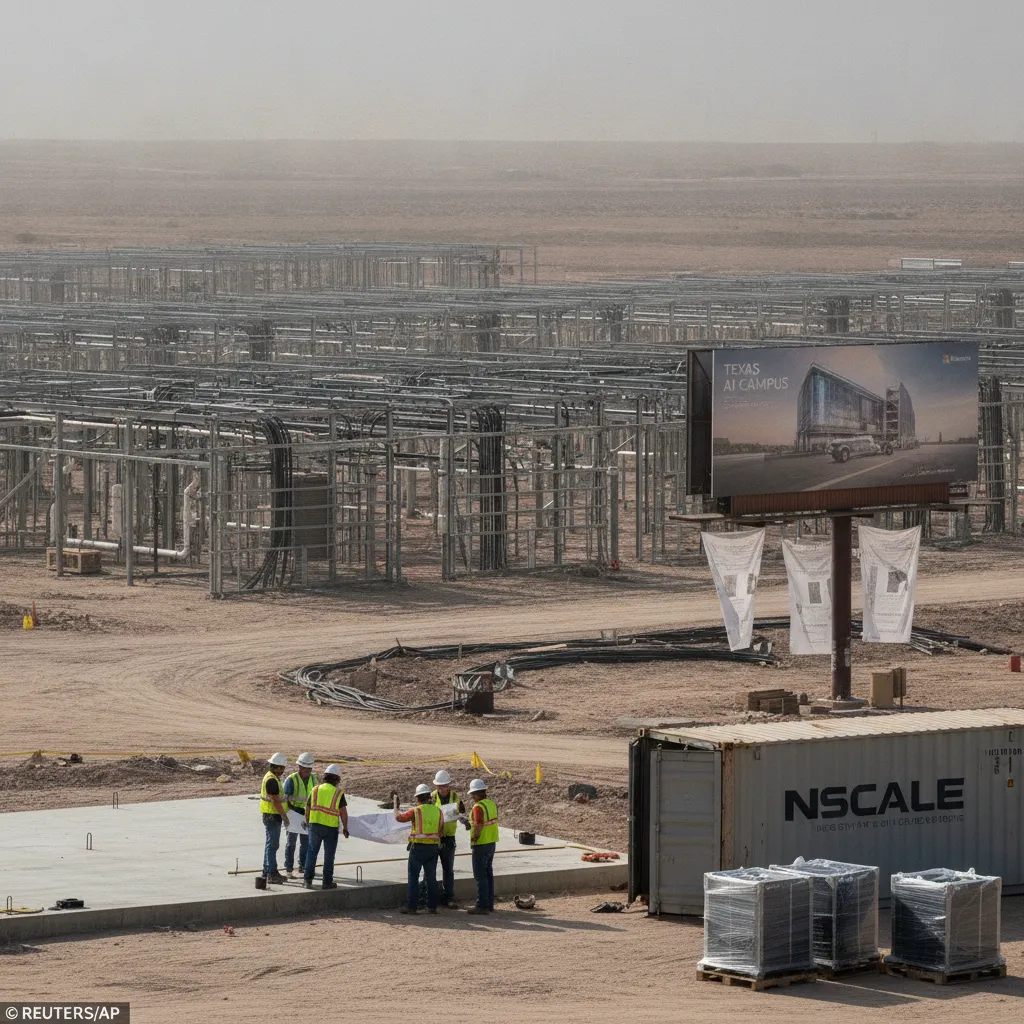
Microsoft appears to be tightening the reins on its partnerships with neocloud providers, shifting toward a more selective approach to acquiring AI computing power. Recent reports suggest the tech giant is distancing itself from riskier ventures and passing on options to expand existing deals, such as a major project in Texas with Nscale. While Microsoft has remained silent on these specific claims, partners like IREN have already signaled shifts in their timelines due to requested design changes from the software leader. This strategic pivot suggests a broader move away from third party rentals in favor of building out its own proprietary data center empire.
At first glance, scaling back external deals might look like a win for a company seeing its free cash flow shrink. However, the financial reality is more complex. Despite strong operational growth, Microsoft’s appetite for infrastructure has led to massive spending spikes that are outpacing incoming cash. In its most recent quarterly reporting period, payments for property and equipment surged to nearly 40 billion dollars, contributing to a steady slide in free cash flow over several years. To keep things moving, Chief Financial Officer Amy Hood recently indicated that the company would seek additional funding sources, evidenced by a recent 25 billion dollar note sale.
The transition from leasing capacity to owning it could actually exacerbate these short term financial pressures. Finance leases allow companies to spread costs over time, whereas building internal sites requires heavy upfront investment. With capital expenditures expected to climb past 50 billion dollars next quarter and future acceleration likely, the immediate hit to the balance sheet could intensify even as Microsoft reduces its reliance on outside vendors.
Despite staggering growth in Azure revenue, which continues to soar near 50 percent, the valuation remains a sticking point for cautious investors. At current prices, Microsoft represents a massive premium relative to its actual free cash flow production. While reducing partnership risks is a prudent long term move for stability and control, it does little to bridge the gap between soaring earnings expectations and dwindling liquid cash. Until the stock sees a meaningful correction or the spending cycle stabilizes, this shift in strategy isn’t enough to turn it into an obvious buy.